Getestet · W7-TEST · Historical simulation
Trading Rush SMA cross: the candle filter matters
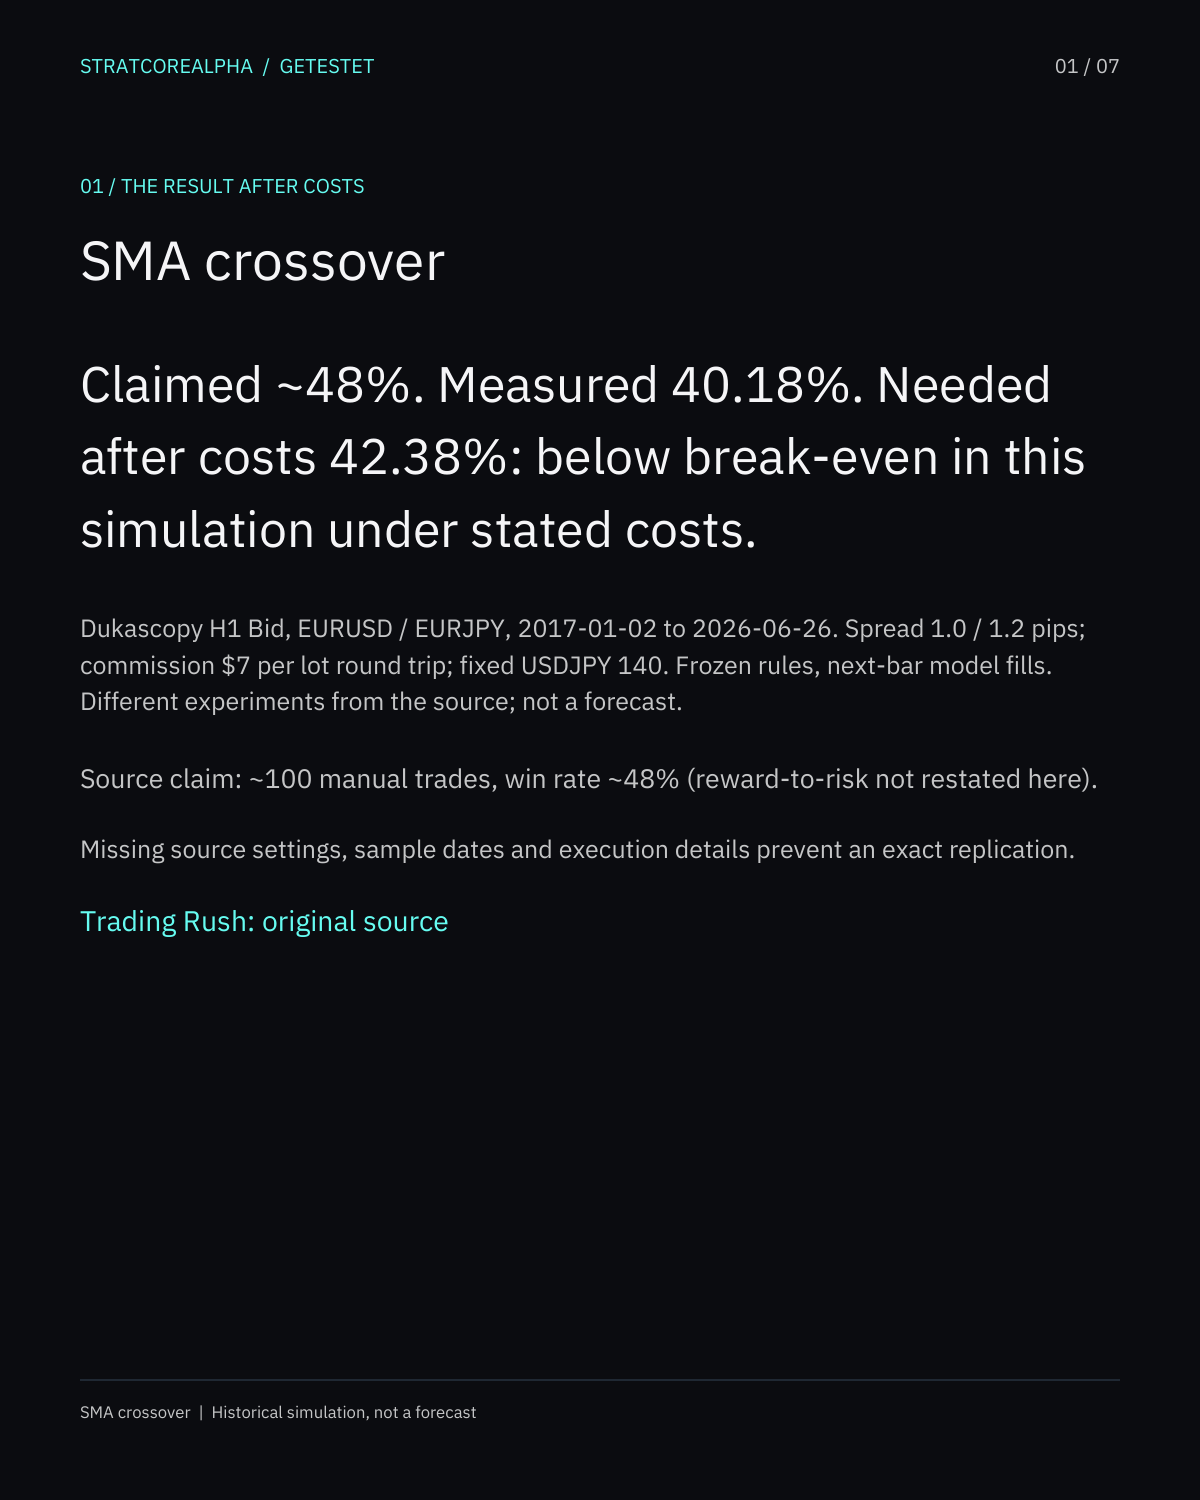
Claimed ~48%. Measured 40.18%. Needed after costs 42.38%: below break-even in this simulation under stated costs.
Trading Rush source claim
~100 manual trades, win rate ~48% (reward-to-risk not restated here).
Original source →Measured under the frozen rules
40.18%1,476 trades, 593 TP / 883 SL / 0 END, win rate 40.18%.
The source and this run are different experiments. Missing settings and sample details prevent an exact replication. Model fills are not observed broker execution. No profit or challenge-pass claim.
The source reports around 48% wins from 100 manual trades. For an EA, “cross,” “whole candle on one side,” and “swing stop” must each have a precise bar-by-bar meaning.
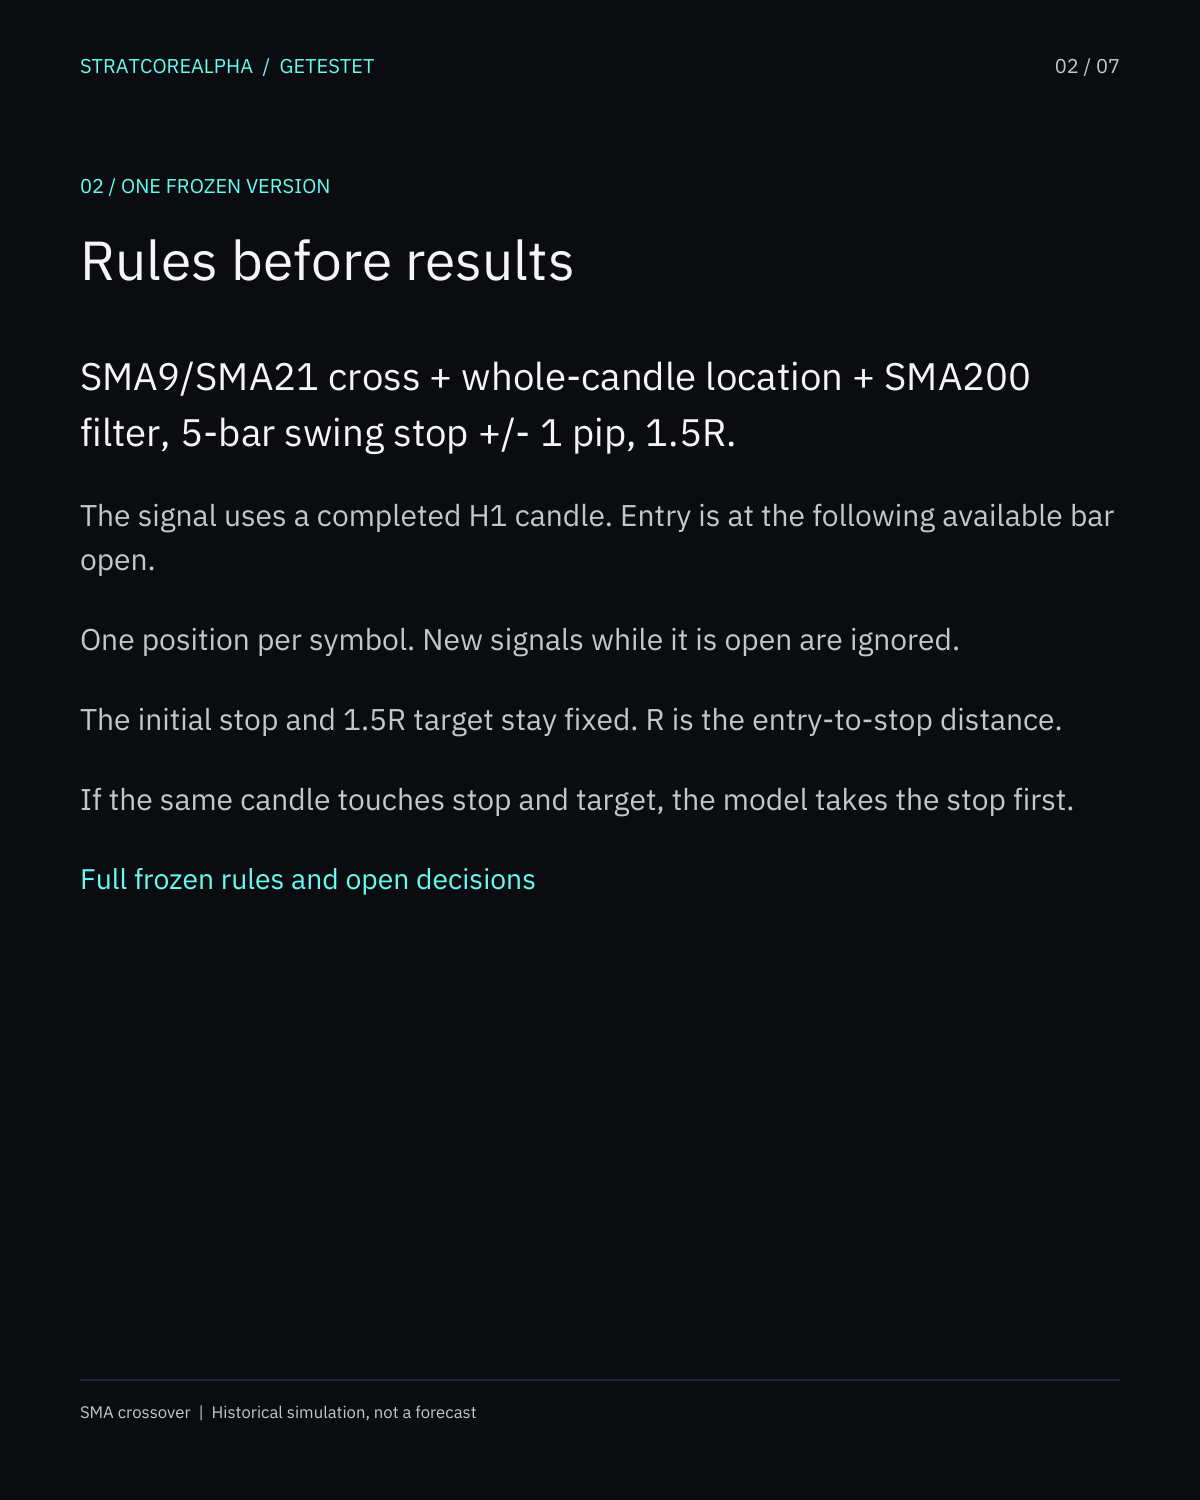
I froze SMA9/SMA21 crossing on completed bars, a whole-candle location check, SMA200 direction, a five-bar swing stop with one pip of room, and a 1.5R target. Entry occurs at the following H1 open. Both Dukascopy bid feeds, EURUSD and EURJPY, cover 2017-01-02 through 2026-06-26. Exits from 2024-01-01 onward form the out-of-sample section. The fixed cost assumptions are 1.0/1.2 pip spread and $7 per lot round trip.
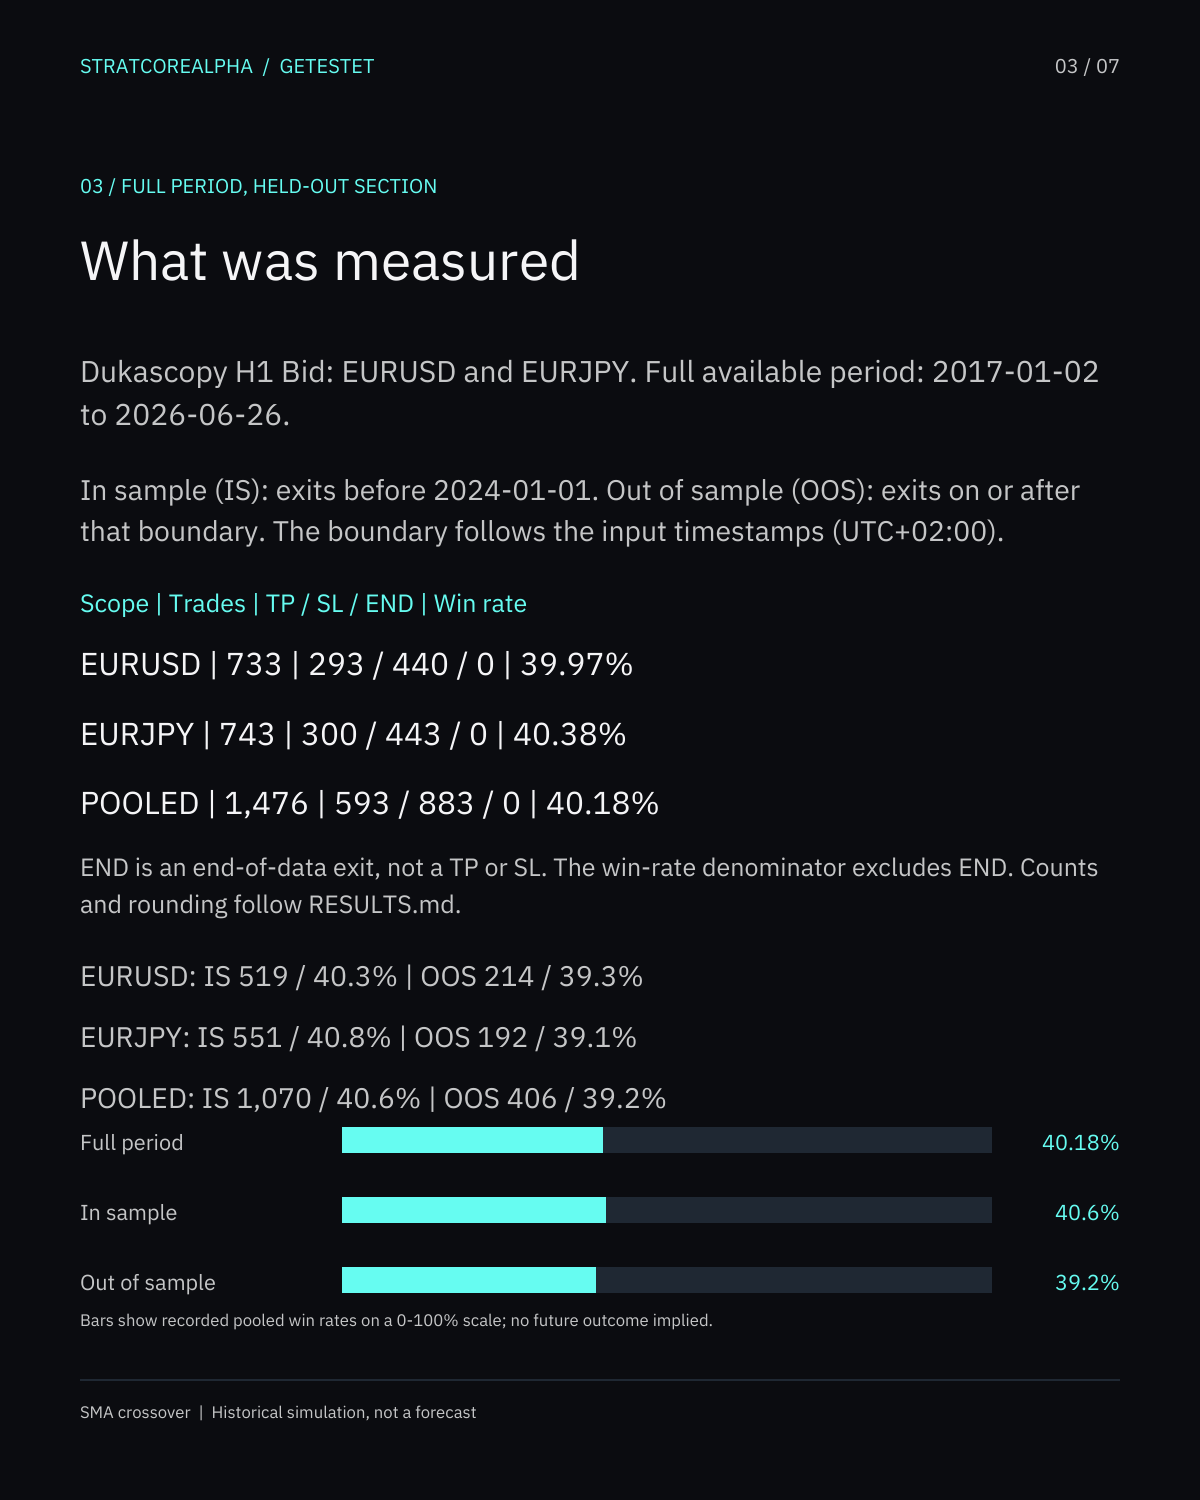
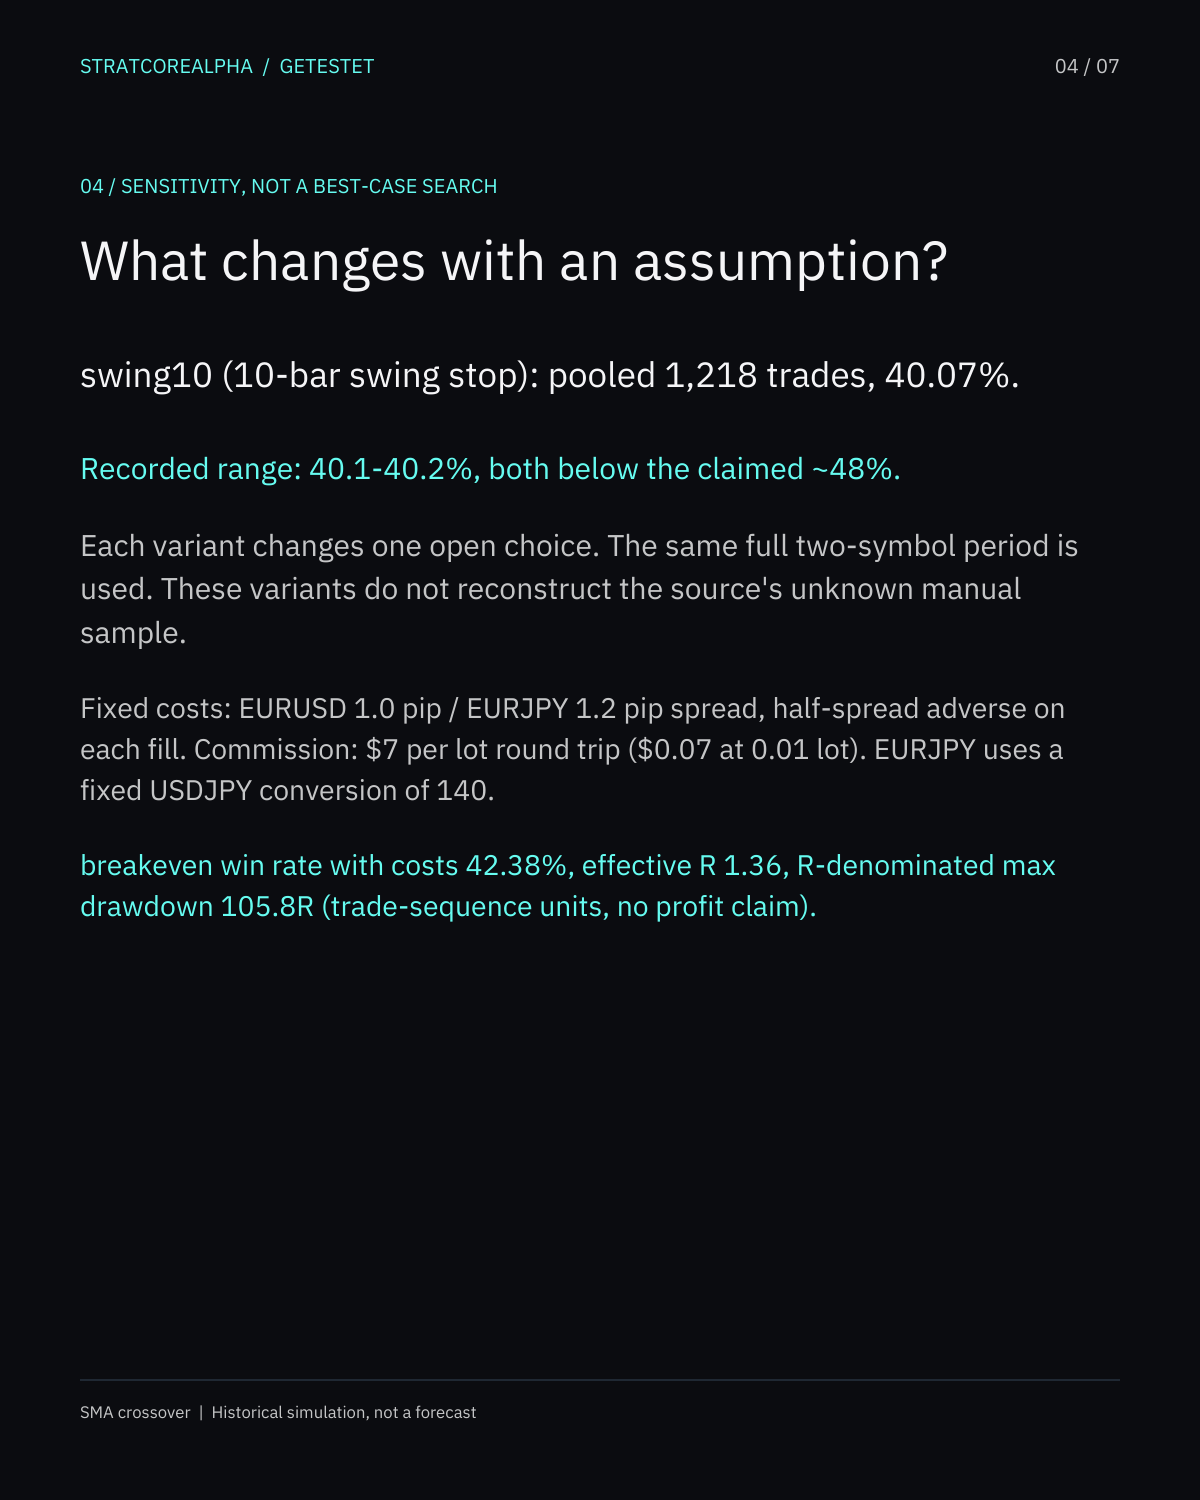
Of 1,476 trades, 593 reached target and 883 reached stop: 40.18% target hits. In sample the rate is 40.6%, out of sample 39.2%. A ten-bar swing-stop variant gives 40.07%. Modeled costs raise the break-even hit rate to 42.38%. These are observations under these rules, not a profit claim.
The video used a manual 30-minute sample and did not pin down the short stop or lookback tightly enough for exact replication. Six base trades touch stop and target within the same H1 bar; the test resolves those to stop because the intrabar path is unavailable. The public rule sheet and trade ledger make the differences inspectable. Check your own rules.
The recorded result
Full period and held-out trades
Dukascopy H1 Bid, 2017-01-02 to 2026-06-26. Split by exit timestamp at 2024-01-01 in the input timezone (UTC+02:00). END is an end-of-data exit and is excluded from the TP/SL win-rate denominator.
| Scope | Trades | TP | SL | END | Win rate | IS (n/rate) | OOS (n/rate) |
|---|---|---|---|---|---|---|---|
| EURUSD | 733 | 293 | 440 | 0 | 39.97% | 519 / 40.3% | 214 / 39.3% |
| EURJPY | 743 | 300 | 443 | 0 | 40.38% | 551 / 40.8% | 192 / 39.1% |
| POOLED | 1,476 | 593 | 883 | 0 | 40.18% | 1,070 / 40.6% | 406 / 39.2% |
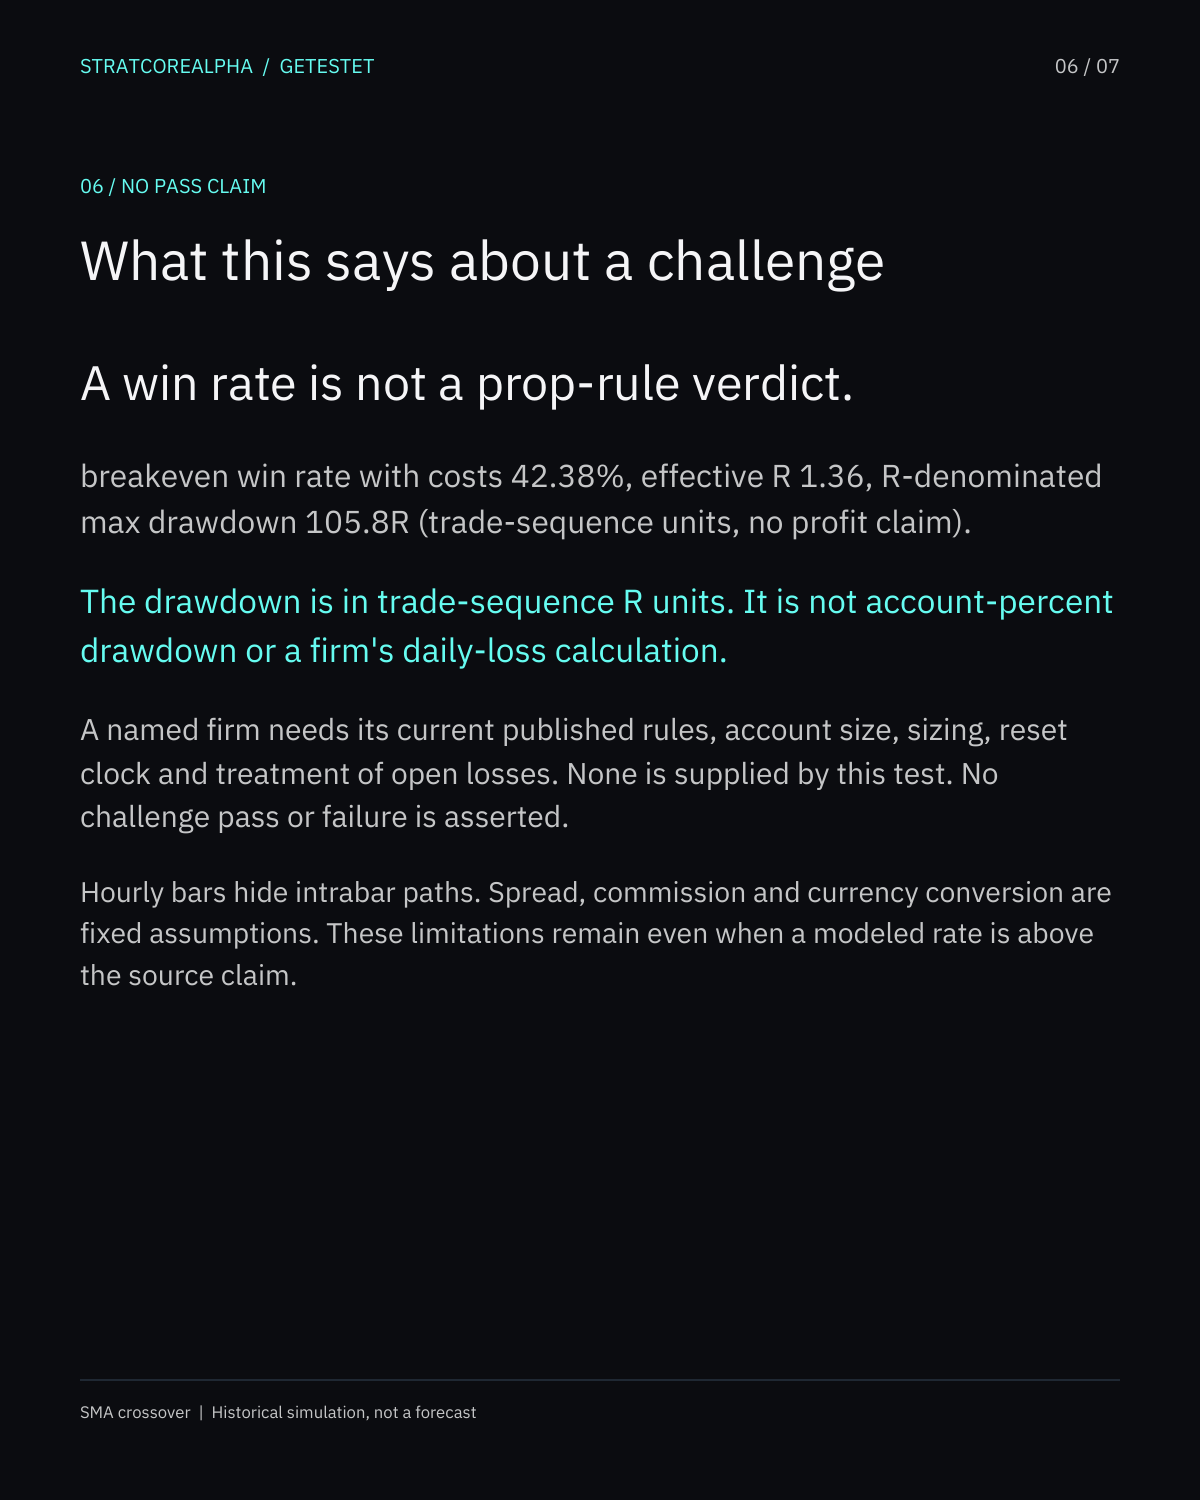
Fixed assumptions: EURUSD 1.0 pip and EURJPY 1.2 pips spread; half-spread adverse on every fill. Commission $7 per lot round trip, $0.07 at 0.01 lot. EURJPY conversion uses fixed USDJPY 140. breakeven win rate with costs 42.38%, effective R 1.36, R-denominated max drawdown 105.8R (trade-sequence units, no profit claim).
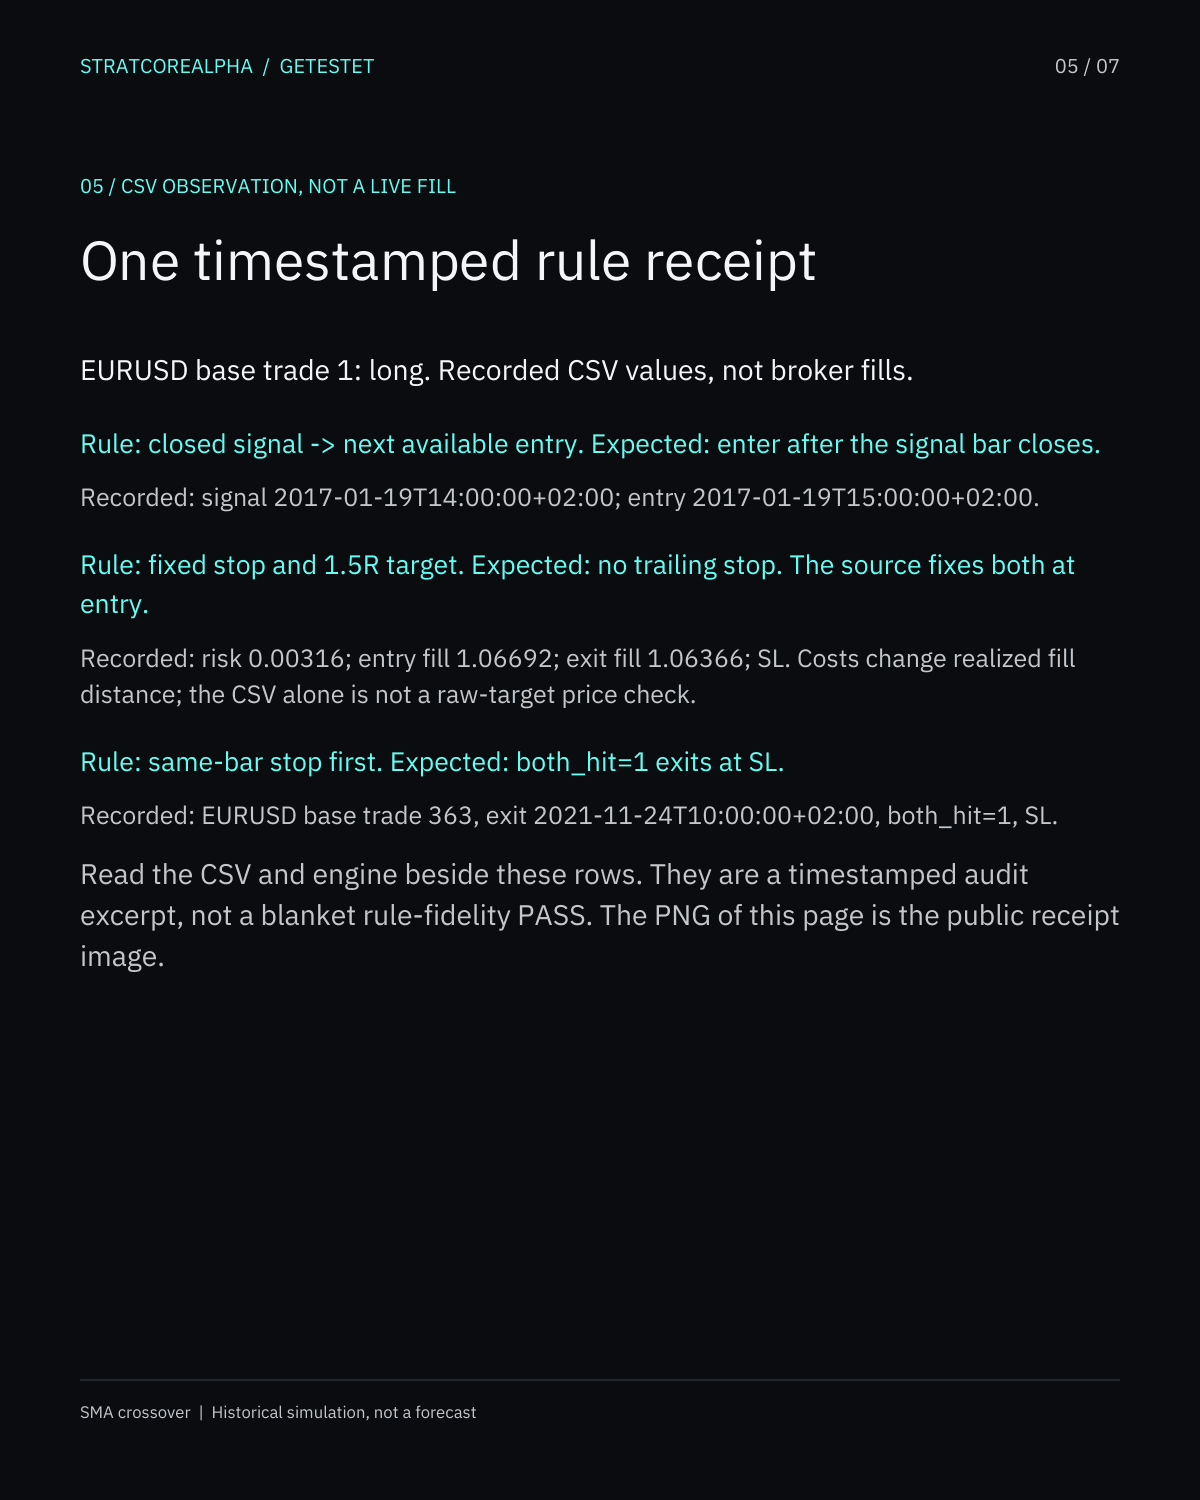
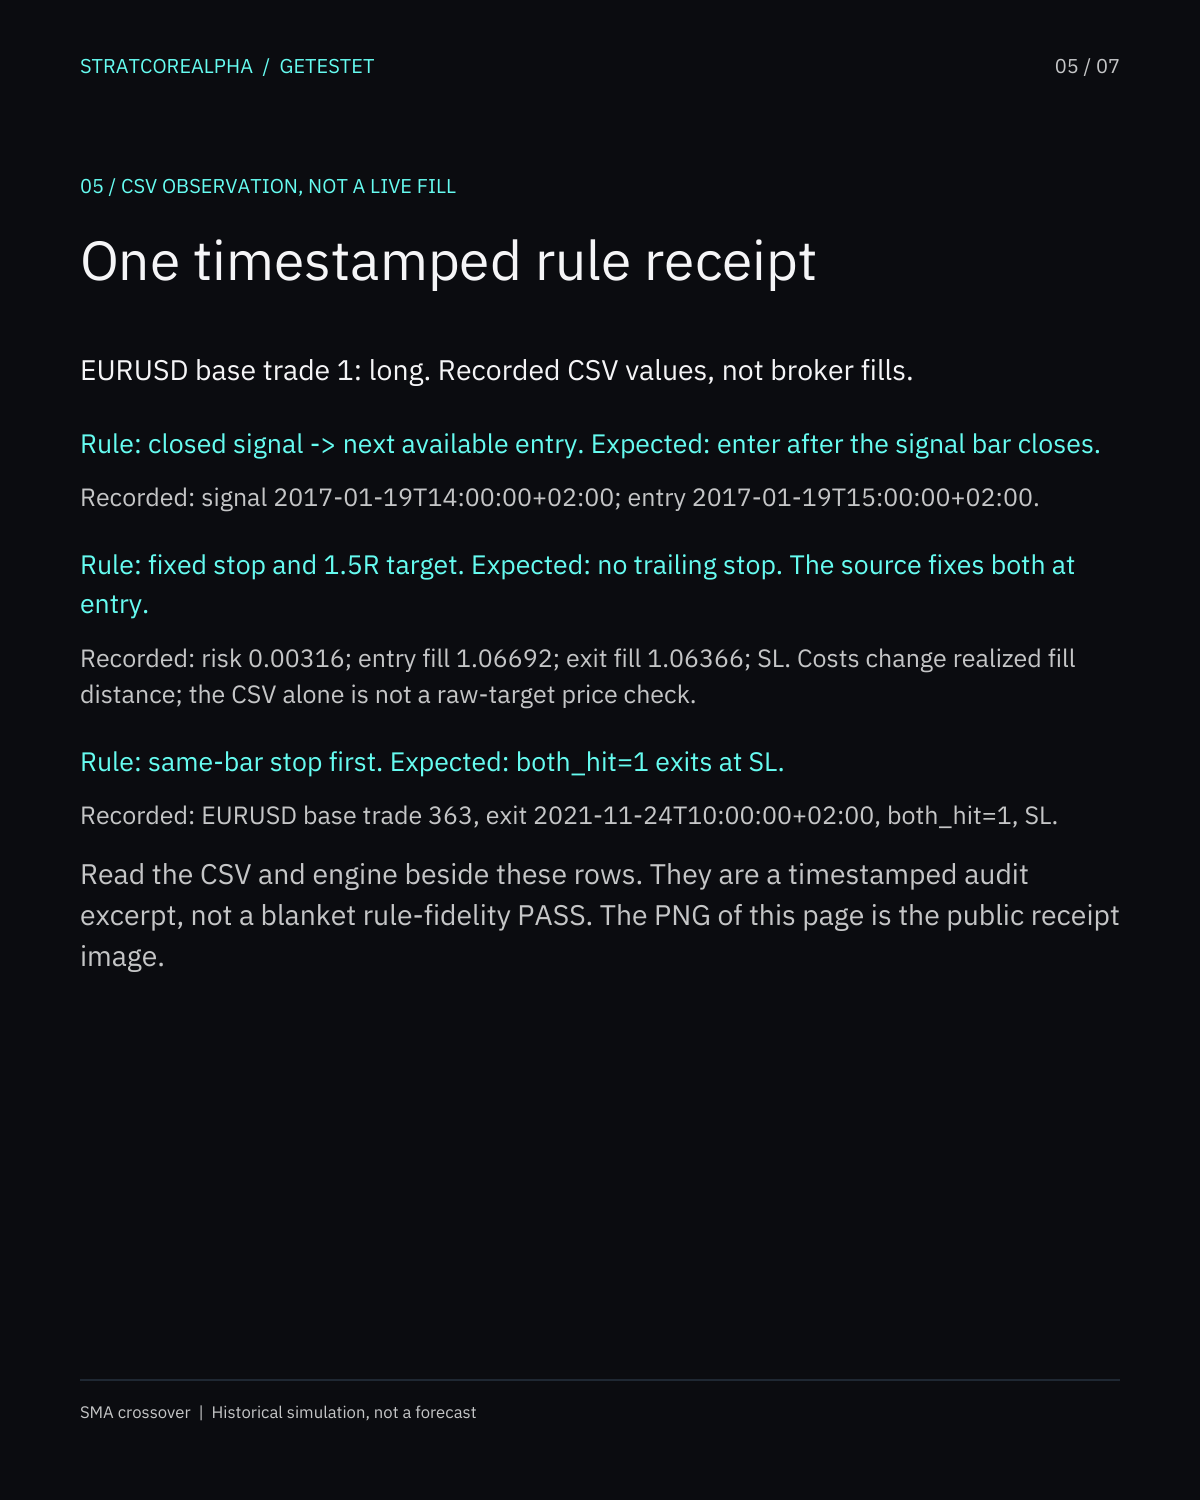
Public rule receipt
Expected rule beside the recorded output
Closed signal and next entry, fixed stop/target, and the same-bar policy. The CSV excerpt names what is observed and what the ledger cannot prove.
No email gate
Seven-page case study and audit files
The PDF and PNG pages share the same content. The CSVs, frozen rules and source code show what was counted. Raw Dukascopy candles are not redistributed.
PNG pages for reading or sharing
Your own case
An EA, a video or notes are enough to start
I write the rules; you confirm them. The direct pilot follows the T99 scope with written feedback within seven days. Current eligibility, allocation and terms are on the pilot page.
I take 5 cases free because I need real cases for my site. Loading the live number of places.
Send your EA, a video or your notesT99 is 99 EUR or USD: one strategy, one symbol, one timeframe, three agreed rule cases, a 12-month historical test and a report with limits. Historical outcomes are not forecasts.