Getestet · W7-TEST · Historical simulation
Does the Supertrend and EMA200 rule repeat 46% wins?
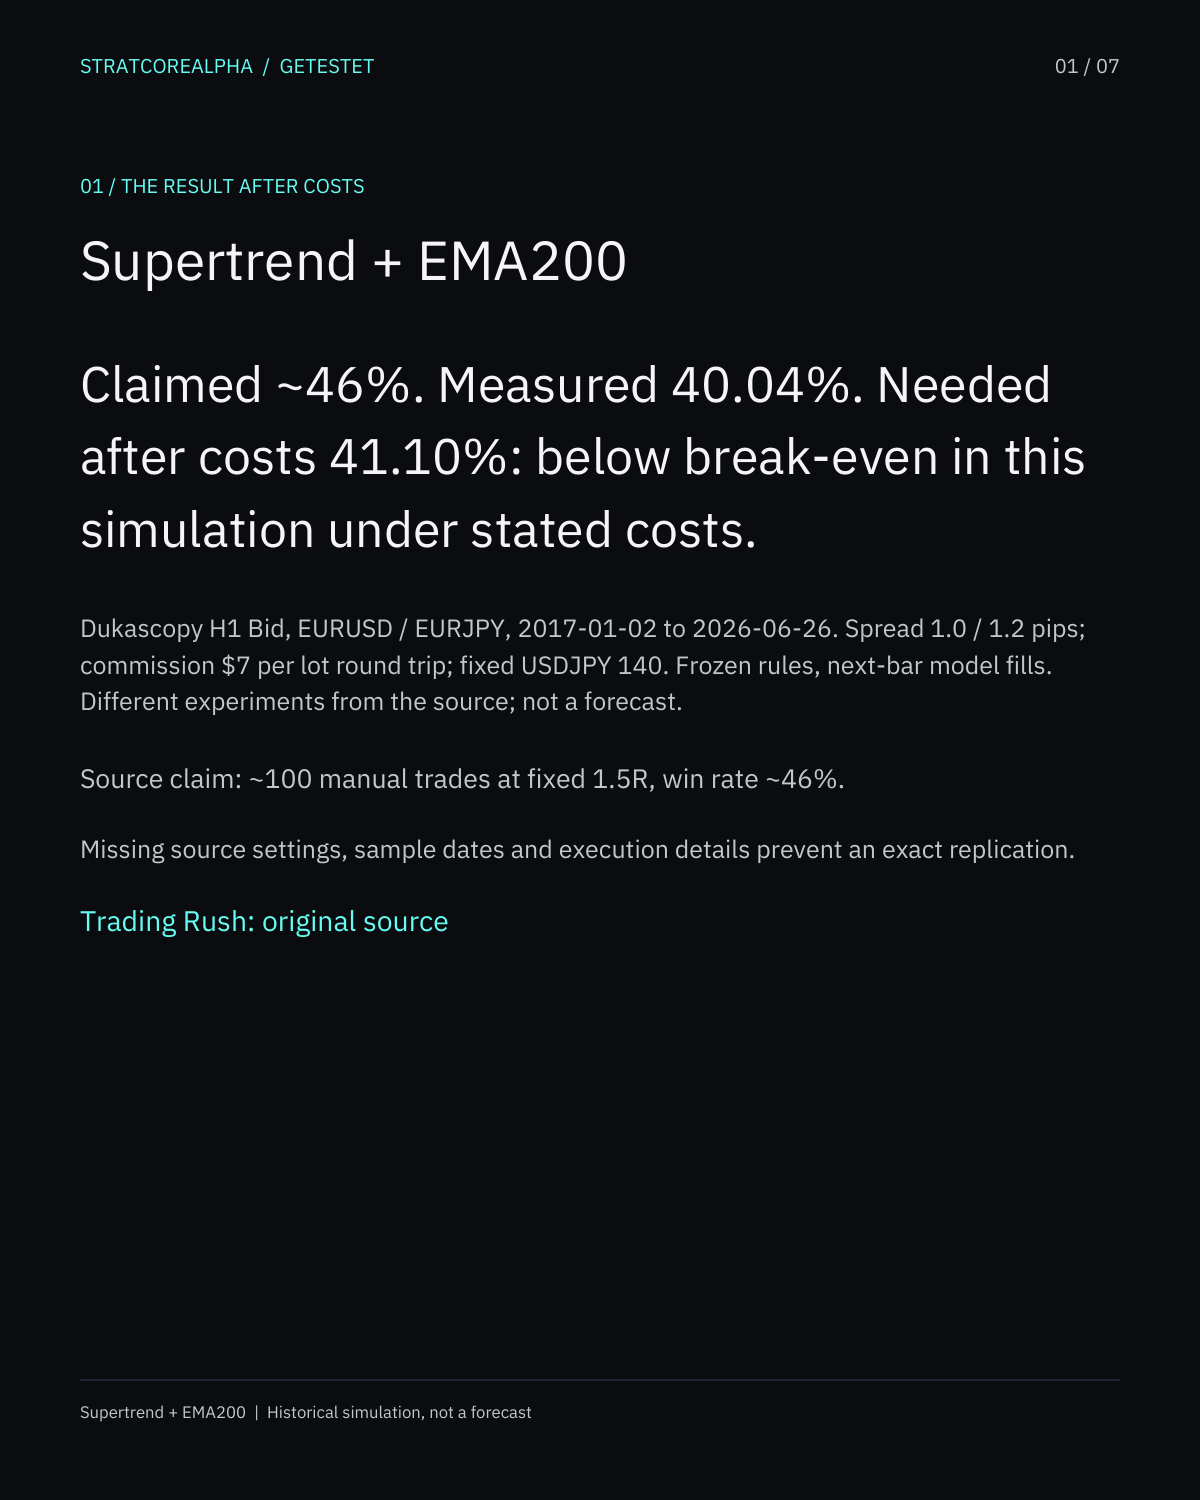
Claimed ~46%. Measured 40.04%. Needed after costs 41.10%: below break-even in this simulation under stated costs.
Measured under the frozen rules
40.04%984 trades, 394 TP / 590 SL, win rate 40.04%.
The source and this run are different experiments. Missing settings and sample details prevent an exact replication. Model fills are not observed broker execution. No profit or challenge-pass claim.
Trading Rush tested about 100 trades with a Supertrend direction change, an EMA200 filter, and a 1.5-to-1 target. The video reports a win rate near 46%. I wanted to answer a narrower question: what happens when I write down one complete version of those rules and run it over every available hour in a longer historical sample?
My result is 40.04% wins across 984 completed trades on EURUSD and EURJPY H1. The video and my test are different experiments. Its exact indicator settings, data dates, and execution assumptions are not available in the claim. The difference between 46% and 40.04% is therefore a reason to inspect the rules, not proof that either count is wrong.
What I fixed before looking at the result
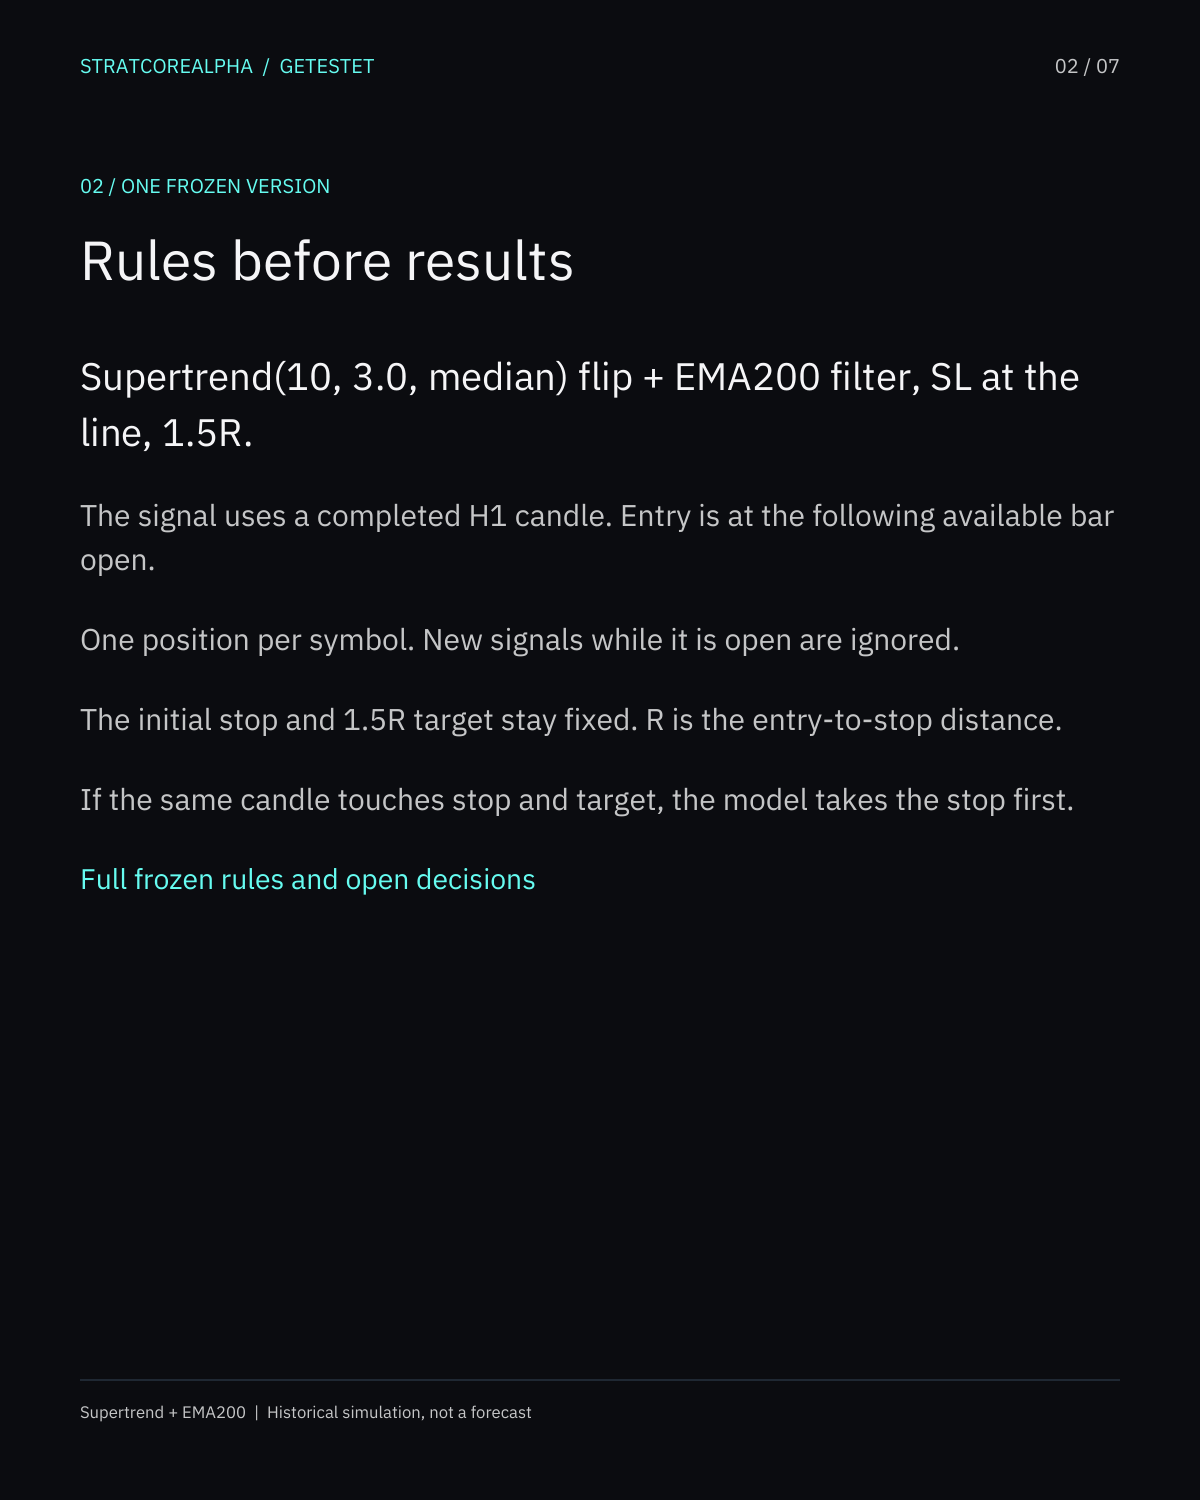
Supertrend is an ATR-based line that changes sides when the trend state flips. I used ATR period 10, multiplier 3, and the candle's median price. A long signal needs the line to flip below the candle and the closed price to be above its 200-hour exponential moving average. A short needs the reverse. The signal is confirmed at the close; the modeled entry happens at the next hour's open. The stop stays at the signal bar's Supertrend line. The target is 1.5 times the distance from entry to stop. Only one position per symbol can be open.
Those values are written in the rule sheet. They are my explicit assumptions where the video leaves room for interpretation. A different Supertrend default, stop buffer, or entry timestamp can change the count. Writing those choices down is the first acceptance test for any strategy that somebody plans to automate.
The data and the result
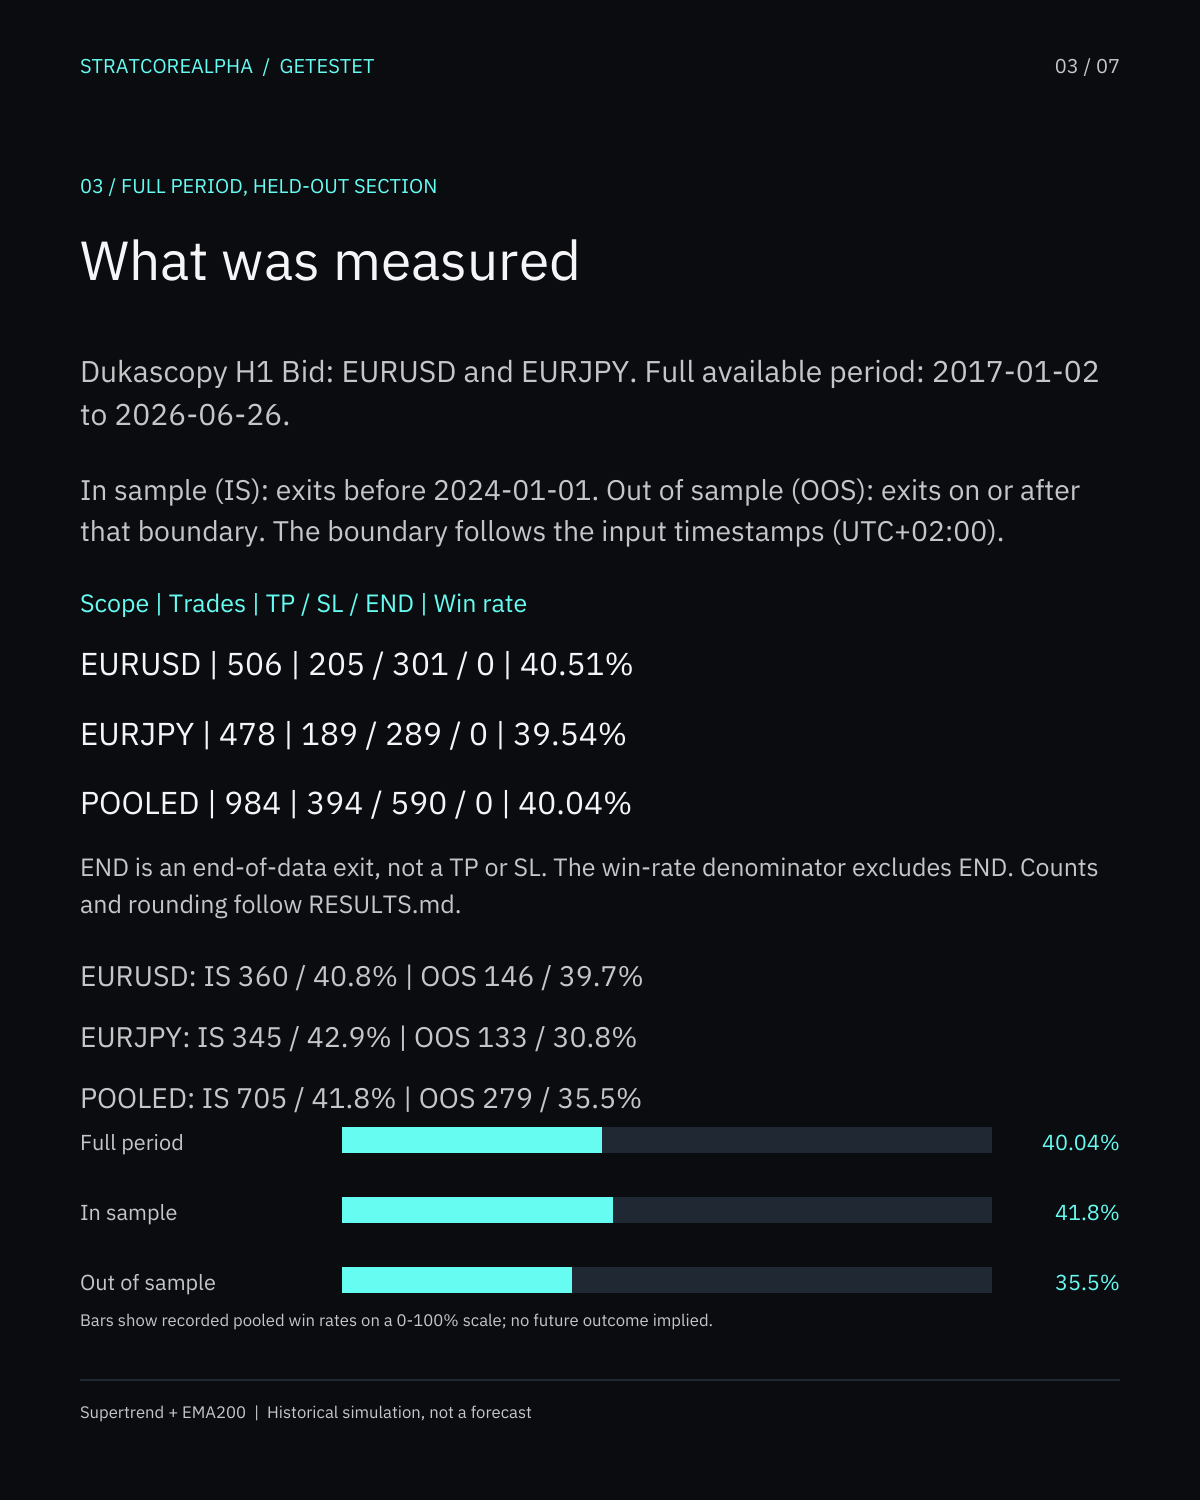
I used official Dukascopy hourly Bid candles from 2 January 2017 through 26 June 2026. The run includes EURUSD and EURJPY, not a selected month around a favorable stretch. I set the split before counting: a trade exiting before 1 January 2024 is in sample; later exits are out of sample. The pooled in-sample win rate was 41.8% on 705 trades. The out-of-sample rate was 35.5% on 279 trades. The separate symbol rates were 40.51% for EURUSD and 39.54% for EURJPY.
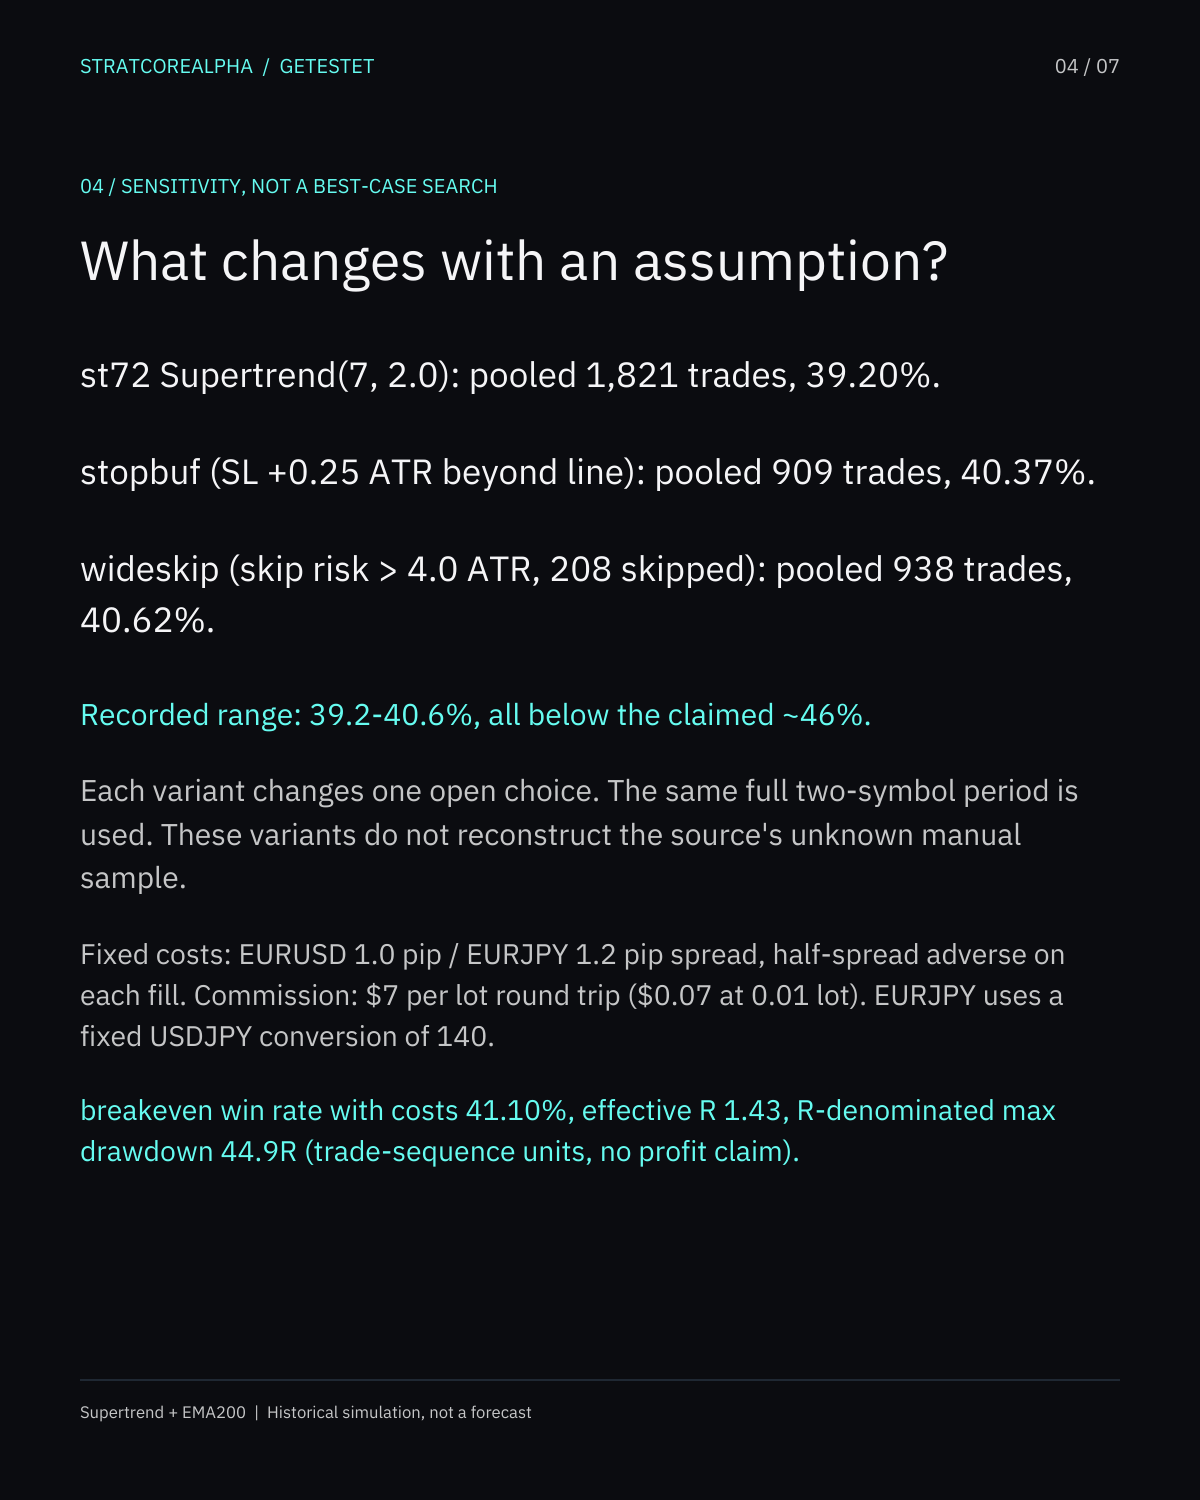
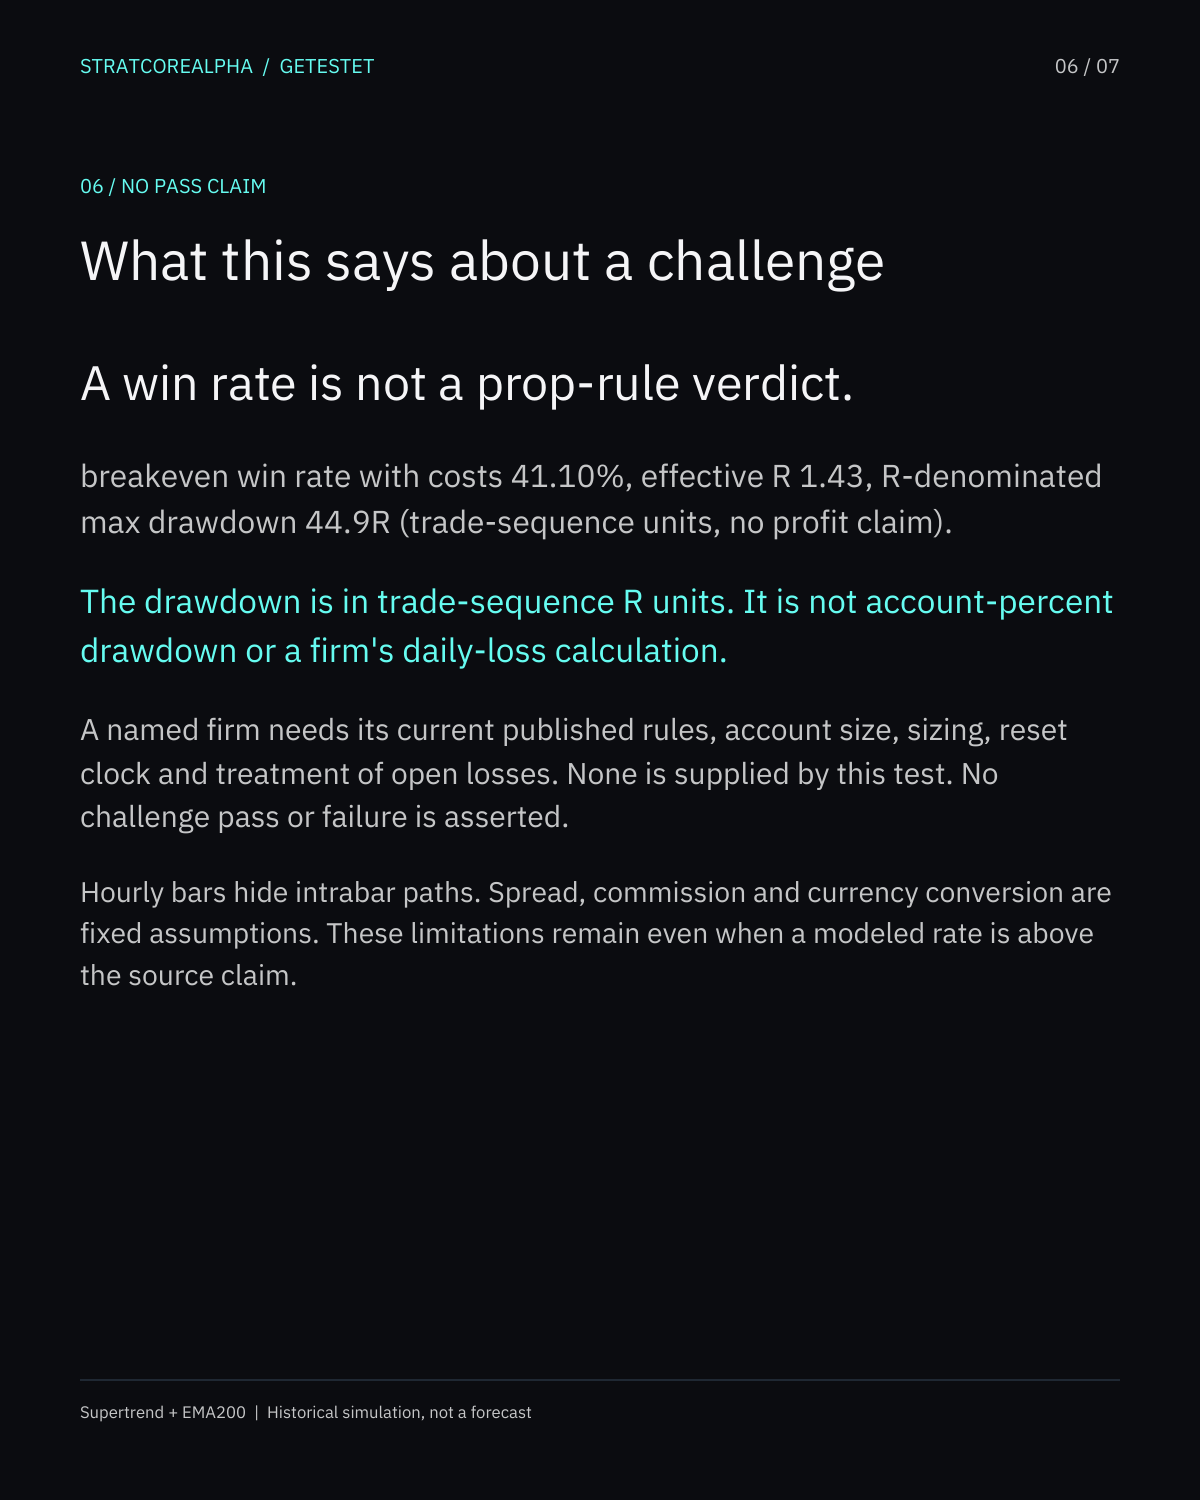
These data are Bid candles, so Ask-side execution must be modeled. I fixed 1.0 pip spread for EURUSD, 1.2 pips for EURJPY, and $7 per standard lot round-trip commission. The EURJPY commission uses a fixed USDJPY conversion of 140. These are cost assumptions, not a claim about any broker's historical fills. At the tested 1.5R target and modeled costs, the pooled breakeven win rate is 41.10%. The base run's 40.04% sits below that threshold. The R-denominated maximum drawdown in the trade sequence was 44.9R. This is a historical simulation, not a forecast.
I changed only one uncertain choice at a time. A faster Supertrend setting produced 39.20% over 1,821 trades. Moving the stop 0.25 ATR beyond the line produced 40.37% over 909. Skipping unusually wide stops produced 40.62% over 938. The range across those three alternatives is 39.2% to 40.6%. It did not recover the video's approximate 46% in this dataset.
Three checks before treating the rule as code
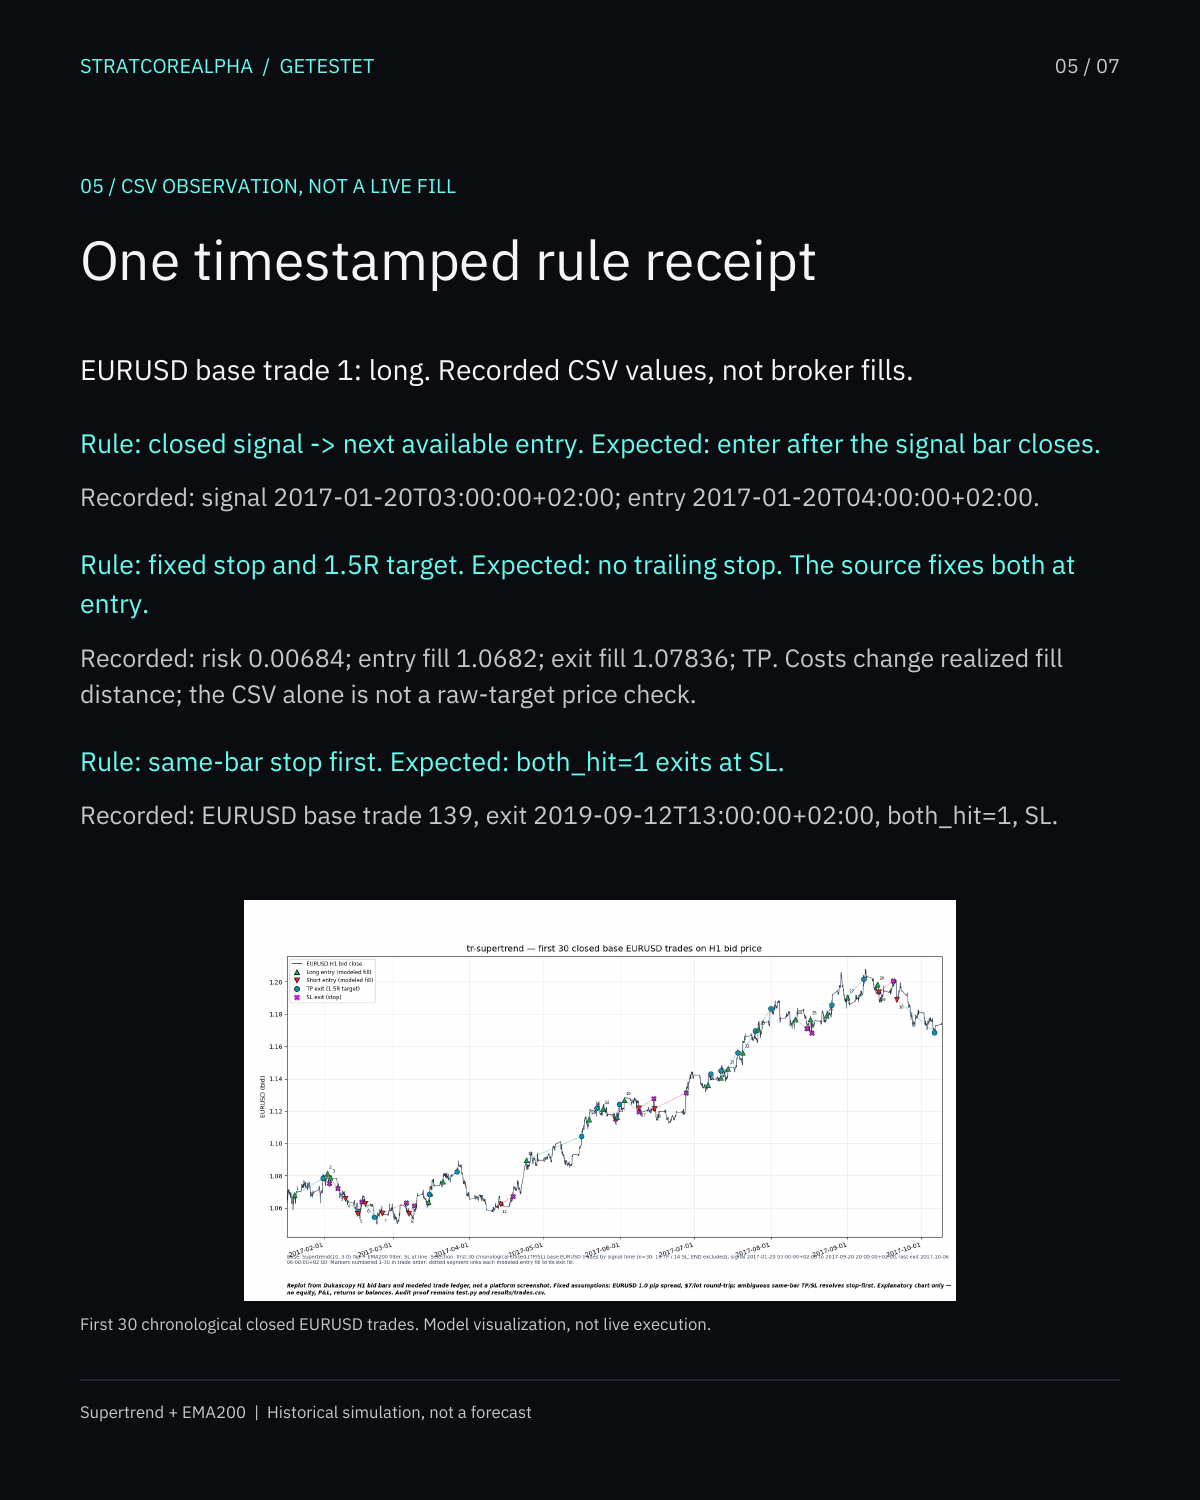
First, freeze the signal timing. A chart can display a flip inside an unfinished candle, while a backtest using closed bars cannot take it until the next candle. The acceptance case is a known flip bar: the engine must enter once, at the next open, and never on an earlier timestamp.
Second, freeze the stop and target at entry. For one known trade, calculate the distance from entry to the Supertrend line and verify the 1.5R target in the trade CSV. A later movement of the line must not silently change a fixed stop. If a trailing stop is wanted, it is a different rule and needs its own test.
Third, resolve a candle that touches both levels. Hourly OHLC data do not tell us which price was touched first. This test takes the stop first. One pooled base trade has that ambiguity. A different policy could move an individual trade's result, so it belongs in the specification and the acceptance cases.
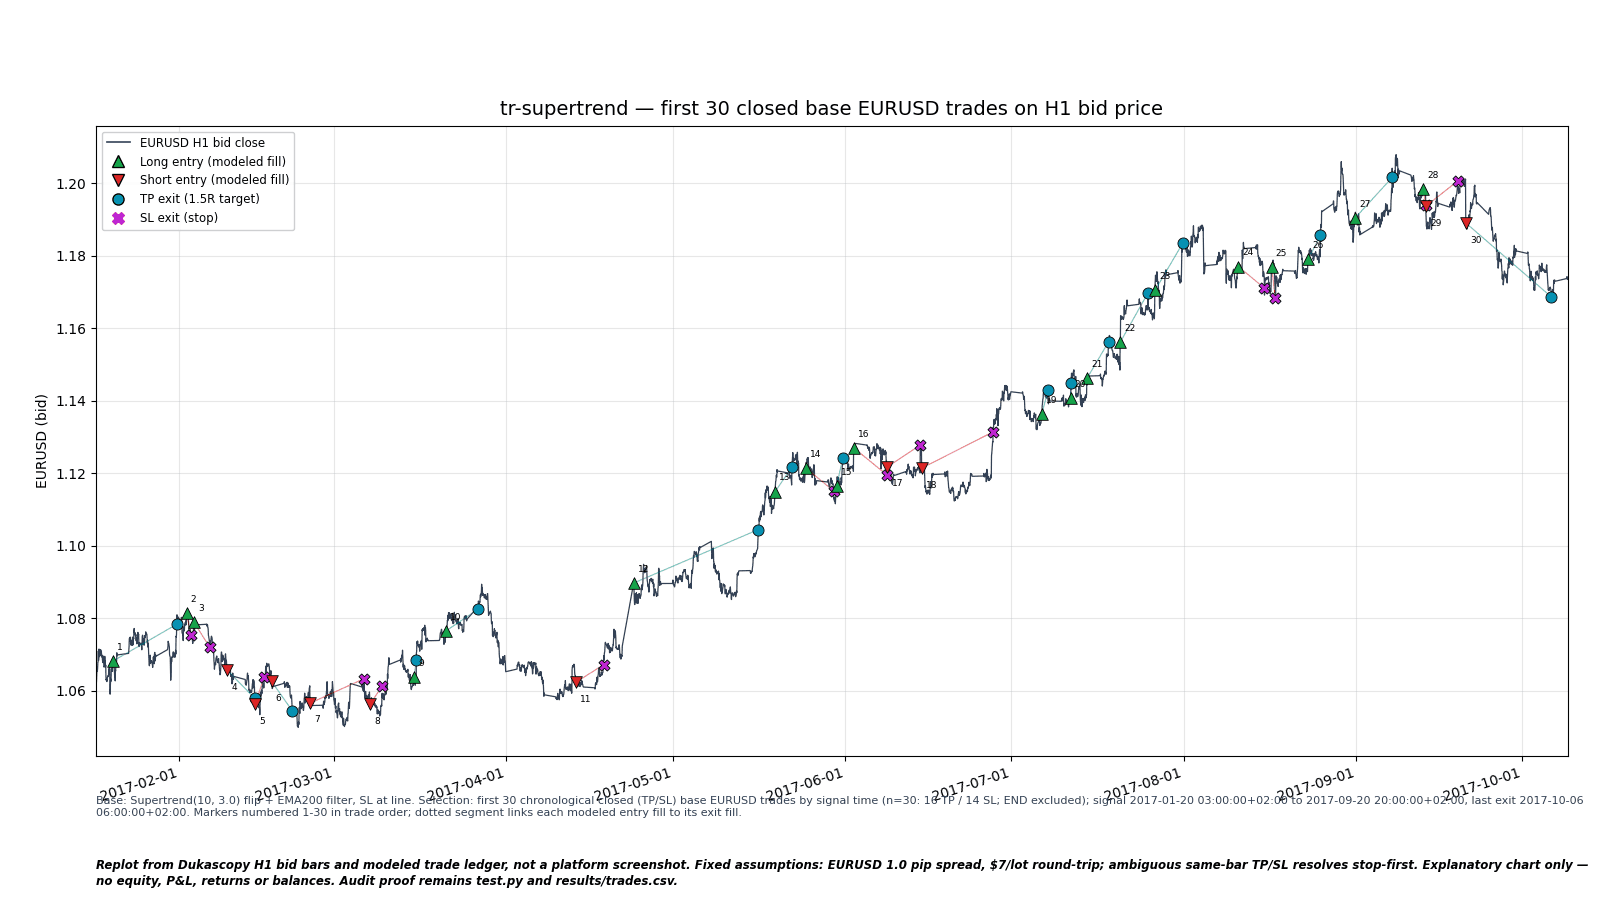
The result sheet and trade CSV show the full count, cost assumptions, variants, and script. The figure of the first 30 chronological EURUSD trades explains the signal and exit rules; it is not evidence of a live run. The test does not reproduce Trading Rush's manual sample, guarantee future results, or show whether any prop firm would allow the rule.
If you have your own Supertrend rule, the useful first step is to write the unresolved choices down. The rule check is a way to do that before commissioning a historical test. One frozen rule set and three acceptance cases are more useful than one headline win rate.
The recorded result
Full period and held-out trades
Dukascopy H1 Bid, 2017-01-02 to 2026-06-26. Split by exit timestamp at 2024-01-01 in the input timezone (UTC+02:00). END is an end-of-data exit and is excluded from the TP/SL win-rate denominator.
| Scope | Trades | TP | SL | END | Win rate | IS (n/rate) | OOS (n/rate) |
|---|---|---|---|---|---|---|---|
| EURUSD | 506 | 205 | 301 | 0 | 40.51% | 360 / 40.8% | 146 / 39.7% |
| EURJPY | 478 | 189 | 289 | 0 | 39.54% | 345 / 42.9% | 133 / 30.8% |
| POOLED | 984 | 394 | 590 | 0 | 40.04% | 705 / 41.8% | 279 / 35.5% |
Fixed assumptions: EURUSD 1.0 pip and EURJPY 1.2 pips spread; half-spread adverse on every fill. Commission $7 per lot round trip, $0.07 at 0.01 lot. EURJPY conversion uses fixed USDJPY 140. breakeven win rate with costs 41.10%, effective R 1.43, R-denominated max drawdown 44.9R (trade-sequence units, no profit claim).
A reader's cost question
Does this backtest include costs?
Yes: the reported simulation includes the stated spread and round-trip commission. Keep the amount, unit, side and currency together before comparing it with your own challenge EA.
The fixed spread is applied as an adverse half-spread on every fill. Commission is 7 USD per lot for the round trip, or 0.07 USD at the stated 0.01-lot size. That is a complete entry-and-exit assumption, not a fee to charge again in full on each side. The EURJPY commission conversion uses a fixed USDJPY value of 140. These inputs are copied from the frozen RESULTS.md, not inferred from your broker.
A cost number without its unit describes an incomplete test
A percentage of trade value, a cash amount per order and a cash amount per lot are different inputs. Before reusing a report, check which input the engine accepts and whether it applies on entry, exit or both. Keep the position size and account-currency conversion beside it. A plausible total does not establish that the fee was charged in the intended way.
Three checks before using the result for your own EA
- Read one completed trade's entry and exit records beside the cost settings. Check the spread side, commission unit and round-trip treatment against the rule sheet.
- When changing position size or symbol, check how the declared commission and currency conversion are applied. Do not carry over a cash fee without its sizing rule.
- Keep the gross and stated-cost versions distinct if you compare them. A change to the cost rule is a different simulation configuration, not a newly verified result of this frozen run.
These are proposed checks for your own test, not additional runs reported here. Fixed assumptions make this historical simulation reproducible. They do not reproduce changing spreads, actual fills or a particular broker's charges, and they do not establish that an EA would pass a challenge.
Read the recorded costs and limits → · Strategy-test hub → · Describe the rule you want checked →
A reader's sensitivity question
Did only the declared rule change?
Keep the base, every variant and the held-out split together. A parameter comparison needs the same data, costs and execution assumptions before its numbers can be interpreted.
A reader asked for parameter sensitivity and out-of-sample checks. This frozen experiment keeps EURUSD and EURJPY, Dukascopy H1 bid data from 2017-01-02 to 2026-06-26, the stated costs and the exit-date split at 2024-01-01. In this simulation under stated costs, the base and variants answer a bounded sensitivity question. They do not reproduce a changing live spread or a prop account's intraday value.
| Recorded variant | Declared change | Pooled trades | Measured win rate |
|---|---|---|---|
| Base | Supertrend 10 / 3.0 and EMA200 filter | 984 | 40.04% |
| st72 | Supertrend 7 / 2.0 | 1,821 | 39.20% |
| stopbuf | Stop plus 0.25 ATR beyond the line | 909 | 40.37% |
| wideskip | Skip risk above 4.0 ATR | 938 | 40.62% |
Sensitivity is not a new untouched test
The base retains 705 in-sample trades at 41.8% and 279 held-out trades at 35.5%. Those are the frozen RESULTS.md rows, not newly calculated measurements. If a rule is chosen after viewing the held-out result, that period is no longer an untouched check of the new selection. Preserve the selection date and a new run record instead of carrying over the original claim.
- Compare the input manifests before comparing results: data, symbols, dates, cost units, signal timing and same-bar policy.
- List every declared change. A hidden cost or feed change invalidates a comparison labelled as changing only one rule.
- Keep all variants and both market rows visible. A selected percentage alone does not describe the experiment.
These are checks for interpreting the existing simulation, not extra runs or a profit promise. H1 intrabar paths remain unknown, fills remain modeled, and the fixed cost assumptions remain assumptions.
Read the public reader question → · Frozen measurements and limits → · Strategy-test hub → · Describe your own rule →
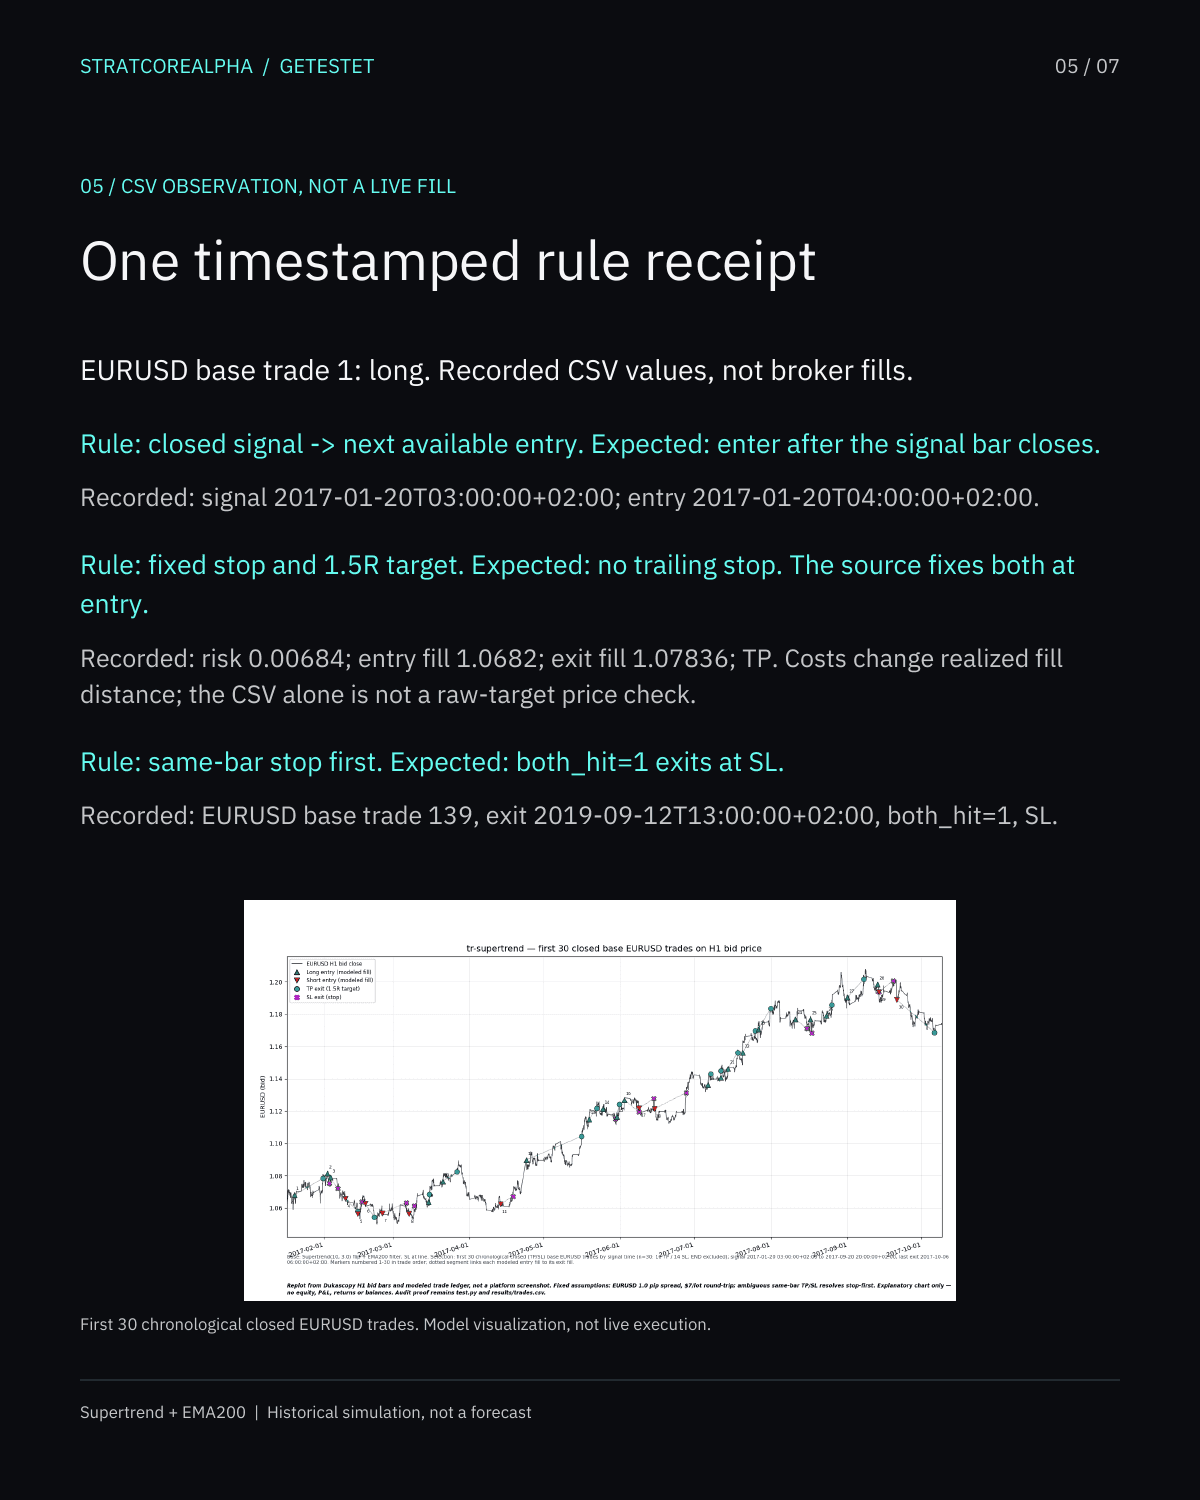
Public rule receipt
Expected rule beside the recorded output
Closed signal and next entry, fixed stop/target, and the same-bar policy. The CSV excerpt names what is observed and what the ledger cannot prove.
No email gate
Seven-page case study and audit files
The PDF and PNG pages share the same content. The CSVs, frozen rules and source code show what was counted. Raw Dukascopy candles are not redistributed.
PNG pages for reading or sharing
Your own case
An EA, a video or notes are enough to start
I write the rules; you confirm them. The direct pilot follows the T99 scope with written feedback within seven days. Current eligibility, allocation and terms are on the pilot page.
Free Prop Rule Guard. Strategy Tester always, 7 days on a broker demo. Prop and real accounts blocked.
Try the free Prop Rule GuardT99 is 99 EUR or USD: one strategy, one symbol, one timeframe, three agreed rule cases, a 12-month historical test and a report with limits. Historical outcomes are not forecasts.